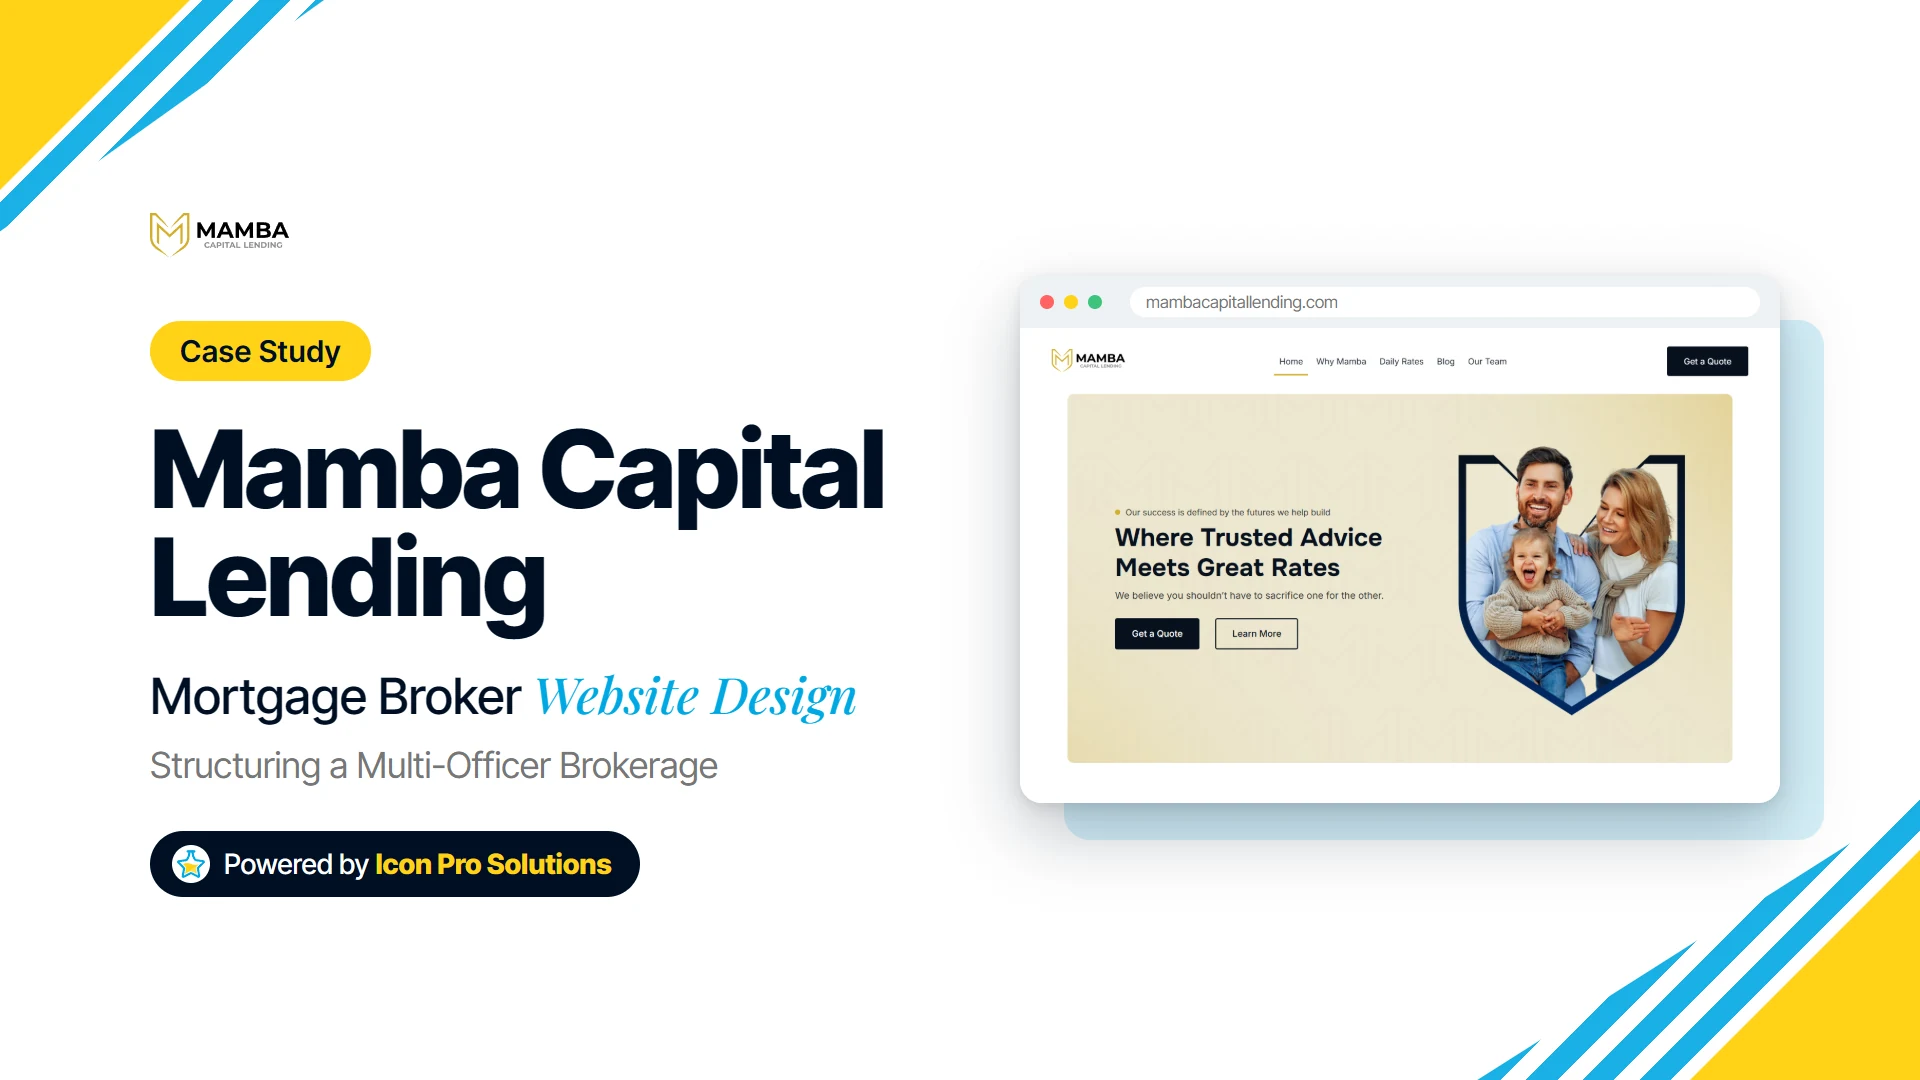
Mamba Capital Lending is a mortgage brokerage in Irvine, California, and its website has to speak for a firm and for every licensed person inside it at once. A single broker’s site can lean on one face and one licence number. A brokerage with more than a dozen loan officers has to show who each person is, which licence they hold, how to reach them, and which rules govern everything a visitor submits.
We designed and built the website. This post walks through how a multi-officer brokerage site is structured, using Mamba as the worked example, and where that structure needs care after launch.
Key Takeaways
- For a brokerage, the team page is not an about page: it is the list of licensed people a borrower can actually work with.
- Firm licence numbers belong in the footer of every page, with a link to where they can be checked.
- A quote form in lending sits on top of legal pages: privacy, terms, SMS consent and licensing disclosures.
- A growing brokerage recruits through its site, and the application form should ask about licensing up front.
- The weak point of this structure is drift: people, licences and policy dates change, and the site has to keep up.
What Does Mamba Capital Lending Do?
Mamba Capital Lending describes its work as “mortgage guidance built on clarity, transparency, and informed decision-making.” Its licensing page says it helps consumers evaluate loan options, submit loan applications and coordinate with lenders. The firm lists NMLS# 2767456 and California DRE license 02376820, with its office at 530 Technology Drive in Irvine.
The site’s navigation runs Home, Why Mamba, Daily Rates, Insights, Career, Loan Officers and Get a Quote. Its privacy policy also covers a Mamba IQ mobile app and a web portal, so the website is one of several places a borrower may meet the firm.
Why Does the Team Page Carry So Much Weight?
Because in a brokerage the people are the service. A borrower is not choosing an abstract company, they are choosing the loan officer who will handle their file, and that officer’s licence matters as much as the firm’s.
Mamba’s roster lists 23 people. Each loan officer’s entry carries a name, a title, an individual NMLS ID, a direct phone number and a personal email address, and 14 of them have a link to their own page.
Showing the whole team, not just the sellers
The roster does not stop at the consultants. It lists loan officer assistants, in-house processors, third-party processors and a VP of Funding and Operations, each with their role stated plainly.
That is a deliberate trade-off. A shorter page of senior names looks cleaner, but the fuller list answers a question borrowers rarely ask aloud: who else will see my documents? Labelling a processor as in-house or third party is a small line of text that tells a careful reader how the file actually moves.
Room for more than one licence line
Two officers on the roster carry a second line, the company NMLS number, printed beside their own ID. An entry built as a small record, rather than a name and a title, has room for licensing details that vary from person to person.
Why Put the Firm’s Licences in Every Footer?
Because a borrower may land on any page first, and the licence question comes before the rate question. Mamba’s footer carries the NMLS and DRE numbers, the full address, a phone number, an email address and a link to NMLS Consumer Access on every page.
The footer also holds the legal set: Privacy Policy, Terms of Use, SMS Terms and Conditions, Licensing and Disclosures, a Texas Complaint and Recovery Fund Notice, and an ADA Accessibility Statement. Placing them together tells a visitor the firm expects to be checked. It also means nobody has to hunt for a disclosure that a regulator or a cautious borrower wants to see.
A licensing page that points outward
The Licensing and Disclosures page names the regulators, the Nationwide Multistate Licensing System and the California Department of Real Estate, and prints the lookup address for each. It adds a fair lending statement and the Equal Housing Lender line.
The design choice here is to send the reader away to verify. That runs against the usual instinct to keep visitors on the site, but a licence number the reader cannot check is only a claim.
Why Does a Quote Form Need Three Legal Pages Behind It?
Because in mortgage lending, what happens after a visitor presses submit is regulated too. Mamba’s terms state that nothing on the site is an offer to lend, a loan approval, a rate lock or a commitment. The same point appears again in the privacy policy, the SMS terms and the licensing page.
Consent that is written down
The privacy policy describes an SMS consent checkbox and says consent is not a condition of any purchase, loan application or approval. The SMS terms page repeats the rules a borrower will want: message frequency varies, rates may apply, reply STOP to opt out and HELP for assistance.
A separate page costs a reader’s patience, but it is worth it: a form that collects a phone number without saying what the firm will do with it leaves the brokerage exposed and the borrower guessing.
One policy for several products
The privacy policy is split into sections: one for the website and one for the Mamba IQ app and web portal. It names the outside services the app uses and says the firm does not sell personal information. A site that sits alongside an app needs its policy structured this way, or a reader cannot tell which promises apply to which product.
Why Does a Mortgage Site Recruit?
Because a brokerage grows by adding licensed people, and its own website is where many of them will look first. Mamba’s career page opens with “Now Hiring” and a five-step form: Contact Info, Position, Experience, Licensing and Submit.
Putting licensing in its own step is the useful detail. It sorts applicants early, and it keeps the questions in one short screen at a time instead of one long page. The form also asks how the applicant heard about the firm, with options from LinkedIn to referrals from current staff, which gives the firm a plain record of where each applicant came from.
What We Would Watch
The structure that makes this site useful is also the part that ages fastest.
- The roster. Every hire, departure or title change has to reach the team page quickly, and every NMLS ID has to match the public registry. A roster of 23 people is a lot of small facts to keep true, and in an industry that sells precision, every title and ID deserves a regular check.
- Policy dates. A last-updated date on a privacy policy or terms page is an honest signal, which means an old date is also a signal. Those pages should be reviewed whenever the app, the forms or the licences change.
- Consent wording against real forms. The SMS terms describe a checkbox and what it covers. If a form is later added or changed, the checkbox and the written terms have to change together.
- Blog listings. A blog that publishes daily produces listing cards faster than anyone rereads them. The titles, dates and excerpts on those cards deserve the same review as the posts themselves.
- No outcome figures here. We have no numbers to report for this site, and none are claimed.
Frequently Asked Questions
Should every loan officer at a brokerage have their own page?
For a firm where borrowers choose a person, yes, or at least a full roster entry with licence and contact details. Individual pages give each officer somewhere to send a referral. They also create more pages to keep current.
Why show NMLS numbers so prominently?
Because a borrower can check them. Printing the firm’s number in every footer and each officer’s number on the roster, with a link to NMLS Consumer Access, turns a statement of trust into something the reader can verify.
Does a mortgage website really need separate SMS terms?
If the site collects phone numbers and the firm sends texts, a clear written policy is the responsible choice. Mamba’s states what messages cover, that consent is not a condition of a loan, and how to opt out.
See More of Our Work
Mamba Capital Lending is one of the regulated businesses in our portfolio, where a website has to be accurate before it is anything else. If you run a brokerage and want a site structured around your people and your licences, see our web design service.